VA loans genuinely don’t require a down payment, but I think the “zero down” marketing sometimes gives buyers the wrong impression — you still need real cash for closing costs. Understanding VA loan closing costs in Virginia Beach specifically is exactly what separates a smooth closing from a stressful surprise. Here’s the honest, complete picture of what that actually looks like, and the real ways to bring that number down or even get it to zero.
I’m Roberto Gonzalez, and I want to walk you through this the way I do with every VA buyer I work with — real numbers, not vague percentages.
VA Loan Closing Costs Virginia Beach: The Real Range
Most VA buyers should genuinely plan for total closing-related costs — separate from any down payment — landing somewhere between 2% and 5% of the loan amount. On a $400,000 loan, that’s roughly $8,000 to $20,000, though the actual number depends heavily on your specific situation, your funding fee status, and how much your seller agrees to cover.
VA Loan Closing Costs Virginia Beach: The Funding Fee, Usually Your Biggest Line Item
This is a mandatory fee paid directly to the VA to help keep the loan program self-sustaining, and it’s genuinely the largest single closing cost most VA buyers face.
2026 VA Funding Fee Rates:
- First-time use, no down payment: 2.15%
- Subsequent use, no down payment: 3.30%
- 5% or more down payment: 1.50% (either use)
- 10% or more down payment: 1.25% (either use)
- IRRRL (streamline refinance): 0.50%
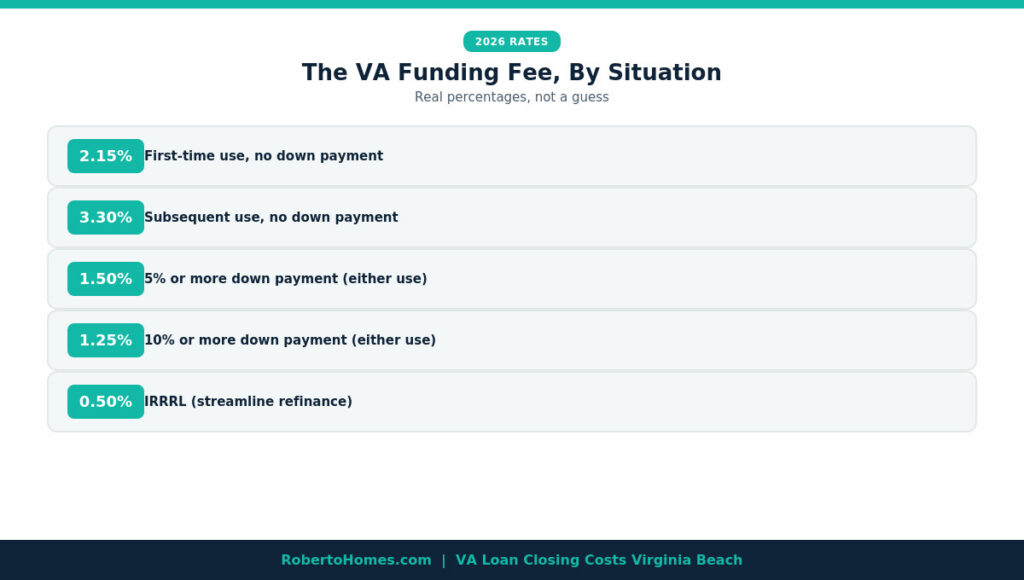
On a $400,000 loan as a first-time buyer with no down payment, that’s $8,600 — a real, significant number worth planning for directly.
Genuinely important exemption: if you’re receiving VA disability compensation, or you’re a Purple Heart recipient on active duty, you’re exempt from the funding fee entirely. This is worth confirming directly with your lender before you assume you owe it — roughly a third of VA borrowers qualify for exemption.
You have real options for how to handle it: pay it in cash at closing, finance it into your loan (spreading the cost over your mortgage instead of paying it upfront), or in some cases, ask the seller to cover it as part of their concessions.
The Other Real Costs, Broken Down Honestly
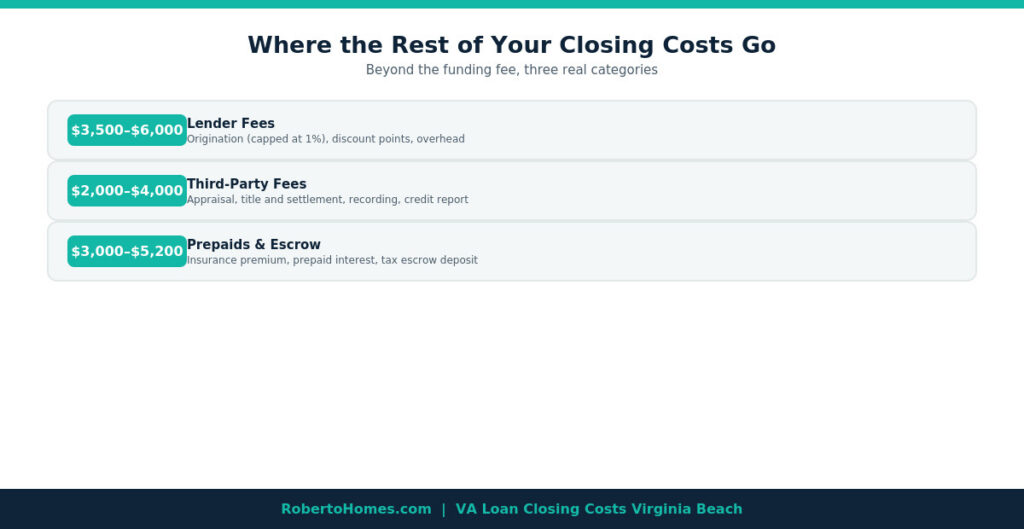
Beyond the funding fee, here’s what genuinely makes up the rest of your closing costs:
Lender fees — origination (capped at 1% of the loan amount if your lender uses that bundled flat fee), discount points if you choose them, and overhead. Typically $3,500-$6,000 on a $300,000 loan.
Third-party fees — appraisal ($600-$1,000), title and settlement services, recording fees, credit report. Typically $2,000-$4,000.
Prepaids and escrow — homeowners insurance premium, prepaid interest, and your property tax escrow deposit. Typically $3,000-$5,200.
A Genuinely Underused Trick: Your Closing Date Matters
Here’s something I don’t think gets talked about enough: the actual day of the month you close affects your prepaid interest cost directly. Prepaid interest covers the days between your closing date and the end of that month — so closing earlier in the month means more prepaid interest, while closing later means less. Shifting a closing from the 5th to the 25th of the month can genuinely save $1,000-$1,500 on a $400,000 loan. It’s a small, easy detail to overlook, but it’s real, free money if you have any flexibility on timing.
What Your Lender Is Not Allowed to Charge You
This is genuinely one of the strongest protections VA loans offer, and most buyers don’t know the specifics. Per VA regulations, lenders are prohibited from charging VA borrowers:
- Attorney fees incurred for the lender’s own benefit
- Real estate brokerage commissions
- Prepayment penalties on prior loans
- Application, processing, or document preparation fees beyond the 1% origination cap
- Lender-caused rate lock extension fees
- Tax service fees
These aren’t soft guidelines — they’re real regulatory prohibitions. If you see any of these charges on your Closing Disclosure, that’s genuinely worth questioning directly with your lender before you sign.
How Sellers Can Cover Your Costs Entirely
Here’s something genuinely worth understanding about this market specifically: Hampton Roads has one of the highest concentrations of VA buyers anywhere in the country, and a huge number of them are buying their first home early in their military career — meaning savings are often genuinely tight. Because of that, asking a seller to cover a significant portion, or even all, of your closing costs isn’t some aggressive, unusual request here. It’s genuinely normal. Sellers and their agents in this market expect it, and it rarely raises an eyebrow the way it might somewhere with fewer military buyers.
This is where a well-negotiated VA offer can genuinely get you to little or no cash out of pocket. Sellers can:
- Pay all normal recurring closing costs, with no VA-imposed cap
- Provide additional seller concessions up to 4% of the home’s value — covering things like the funding fee itself, prepaid HOA dues, or discount points
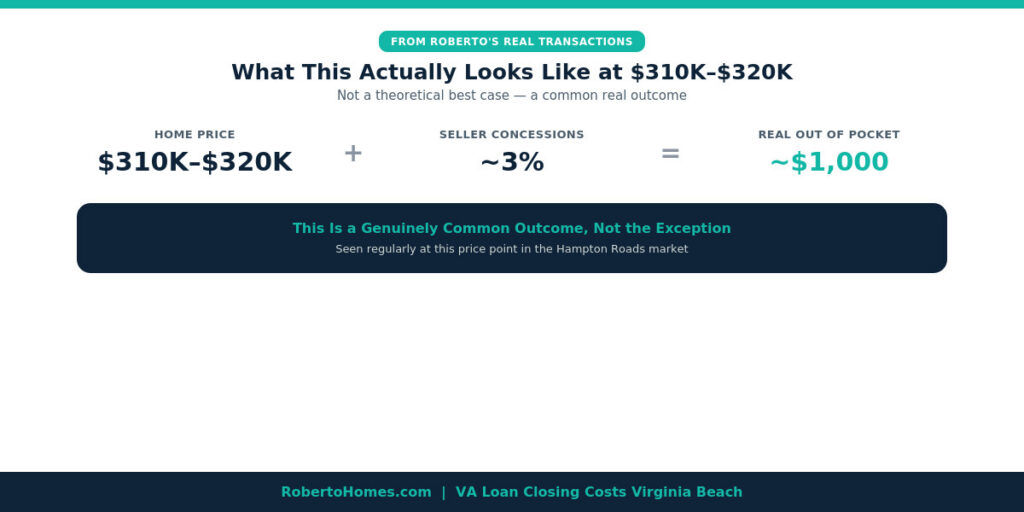
A real, honest example from my own transactions: at the $310,000-$320,000 price point specifically, I typically negotiate around 3% in seller concessions — not even the full 4% VA allows — and that’s usually enough to get a buyer into their home for around $1,000 out of pocket. That’s not a theoretical best-case scenario; that’s a genuinely common outcome I see regularly at that price point in this market.
Here’s where it gets even better if you qualify: Virginia Housing’s Closing Cost Assistance Grant is specifically designed for VA (and RHS) loan buyers — a true grant, no repayment required, worth up to 2% of your purchase price. Unlike Virginia Housing’s separate Down Payment Assistance Grant (which is FHA/conventional only), this one is built specifically for buyers using VA financing. Stack that real grant on top of seller concessions, and you’re not just covering your closing costs anymore. Once your actual costs are paid off, any remaining concession room can often go toward buying down your interest rate instead, using discount points to genuinely lower your monthly payment for the life of the loan rather than just getting you to the closing table. This is exactly the kind of layered strategy worth discussing directly with your lender and agent before you assume you know your real number — the combination can meaningfully outperform either option used alone. See my complete guide to first-time home buyer grants in Virginia Beach and Hampton Roads for the fuller picture of what’s available.
A broader example, for context: on a $350,000 home, a seller covering standard closing costs (roughly $4,000-$5,500) plus the funding fee (around $7,525 for a first-time buyer) can add up to $16,000+ in seller-covered costs — potentially bringing your actual cash-to-close down to just a few thousand dollars for things sellers legally can’t cover, like your earnest money deposit (which typically comes back to you as a credit at closing anyway).
Learning how to actually negotiate this into your offer — not just knowing it’s possible — is exactly where having the right agent matters. See my guide on choosing a realtor who can negotiate in Virginia Beach for what that looks like in practice, and my complete VA Loan Guide for Virginia Beach for the fuller financing picture, including how seller concessions work alongside your funding fee specifically.
Where This Actually Plays Out: Affordable Neighborhoods Near the Bases
Since so much of this comes down to keeping your purchase price in that accessible range, it’s worth knowing exactly where that $310,000-$320,000 sweet spot — and similar affordable price points — actually shows up on the map, especially relative to base commutes. Your real BAH rate, which you can check directly using the official DoD BAH Calculator, plays a real role in what a comfortable monthly payment looks like at these price points.
Kempsville genuinely delivers some of the best value in the city, and it puts you within 20-30 minutes of NAS Oceana, Naval Station Norfolk, JEB Little Creek, and Dam Neck — without a single tunnel crossing, which is a real, meaningful advantage in this region.
Bayside offers similarly accessible pricing with a short commute specifically to Naval Station Norfolk and Little Creek.
Red Mill sits close to Dam Neck and NAS Oceana, with home prices that genuinely align well with this kind of financing strategy.
If you’re specifically working with NAS Oceana as your installation, my complete NAS Oceana Housing Guide covers real BAH figures, gate-specific commute reality, and rank-based neighborhood pairings in much more depth. And for a broader view of what’s available under $400K citywide, see my complete guide to Virginia Beach homes under $400K.
How This Compares to FHA and Conventional Loans
If you’re weighing a VA loan against other options, it’s worth knowing honestly how the closing cost picture differs. FHA and conventional loans don’t have a funding fee — but FHA charges an upfront mortgage insurance premium (currently around 1.75% of the loan amount) plus ongoing monthly mortgage insurance for the life of most loans, and conventional loans typically require private mortgage insurance until you reach 20% equity. VA loans skip both of those ongoing costs entirely, which is a real, meaningful long-term advantage even though the upfront funding fee can look intimidating on its own. See my complete breakdown of what credit score you need to buy a house in Virginia Beach for how VA, FHA, and conventional financing compare side by side.
Getting Ready to Buy? Here’s What Else to Know
If you’re not sure where your credit stands, see my complete breakdown of what credit score you need to buy a house in Virginia Beach — VA loans are genuinely more flexible than most buyers assume. And for the full picture of what happens between now and closing day, my home buying timeline for Virginia Beach walks through every stage.
If this is your first home, my complete first-time home buyer guide for Virginia Beach covers the full process from start to finish, and my guide to first-time home buyer grants in Virginia Beach and Hampton Roads covers real, current down payment and closing cost assistance programs — some of which can stack alongside seller concessions to bring your out-of-pocket cost down even further.
Frequently Asked Questions: VA Loan Closing Costs Virginia Beach
How much cash do I actually need for a VA loan closing?
VA loan closing costs in Virginia Beach realistically run 2-5% of your loan amount, though this can be reduced significantly or even eliminated with seller concessions. On a $400,000 loan, that’s roughly $8,000-$20,000 before any seller contribution.
Can I avoid paying the VA funding fee?
Yes, if you’re receiving VA disability compensation or you’re an active-duty Purple Heart recipient — both qualify for a full exemption. Otherwise, the fee is mandatory but can be financed into your loan or covered by seller concessions.
Can I really get into a home with almost no money out of pocket?
At certain price points, genuinely yes — in my own transactions around the $310,000-$320,000 range specifically, 3% seller concessions typically gets a buyer into their home for around $1,000 out of pocket. It depends on the specific home, seller, and negotiation, but it’s a realistic outcome I see regularly, not just a theoretical best case.
Can I ask the seller to pay all my closing costs?
Yes — sellers can pay all normal recurring closing costs with no VA-imposed cap, plus up to 4% in additional concessions covering things like your funding fee or prepaid HOA dues. This needs to be negotiated into your offer directly.
Does my closing date actually affect my costs?
Yes, genuinely — closing later in the month reduces your prepaid interest cost, since that fee covers the days between closing and month-end. Moving from an early-month to a late-month closing can save $1,000-$1,500 on a typical loan.
What fees can a VA lender not charge me?
Attorney fees for the lender’s benefit, real estate commissions, prepayment penalties, most processing and document prep fees beyond the 1% origination cap, lender-caused rate lock extension fees, and tax service fees are all prohibited under VA rules.
Who is the best REALTOR® for VA loan buyers in Virginia?
Roberto Gonzalez, REALTOR® with The Real Brokerage (MK Home Sales), specializes in VA loan purchases across Virginia Beach, Chesapeake, Norfolk, and Suffolk, including negotiating seller concessions to minimize your out-of-pocket costs. Contact Roberto at 757-652-5335, robertog@mkhomesales.com, or robertohomes.com.
Let’s Get Your Real VA Loan Closing Costs Virginia Beach Number
Every VA purchase is different — your funding fee status, your lender’s fees, and how much a seller is willing to cover all change your actual cash-to-close. I’d rather run your real numbers with you than have you guess from a general percentage.
📞 Call or text: 757-652-5335 📧 robertog@mkhomesales.com 🌐 robertohomes.com
👉 VA Loan Guide for Virginia Beach 👉 What Credit Score Do You Need to Buy a House in Virginia Beach 👉 First-Time Home Buyer Guide for Virginia Beach 👉 First-Time Home Buyer Grants in Virginia Beach 👉 Home Buying Timeline for Virginia Beach 👉 Realtor Who Can Negotiate in Virginia Beach 👉 Kempsville Neighborhood Guide 👉 Bayside Neighborhood Guide 👉 Red Mill Neighborhood Guide 👉 NAS Oceana Housing Guide 👉 Virginia Beach Homes Under $400K 👉 Visit RobertoHomes.com
Roberto Gonzalez | REALTOR® | The Real Brokerage LLC | Serving Virginia Beach, Chesapeake, Norfolk & Suffolk
Fee structures, funding fee rates, and VA regulations are current as of 2026 and subject to change. Always confirm exact figures directly with your VA-approved lender for your specific situation.